

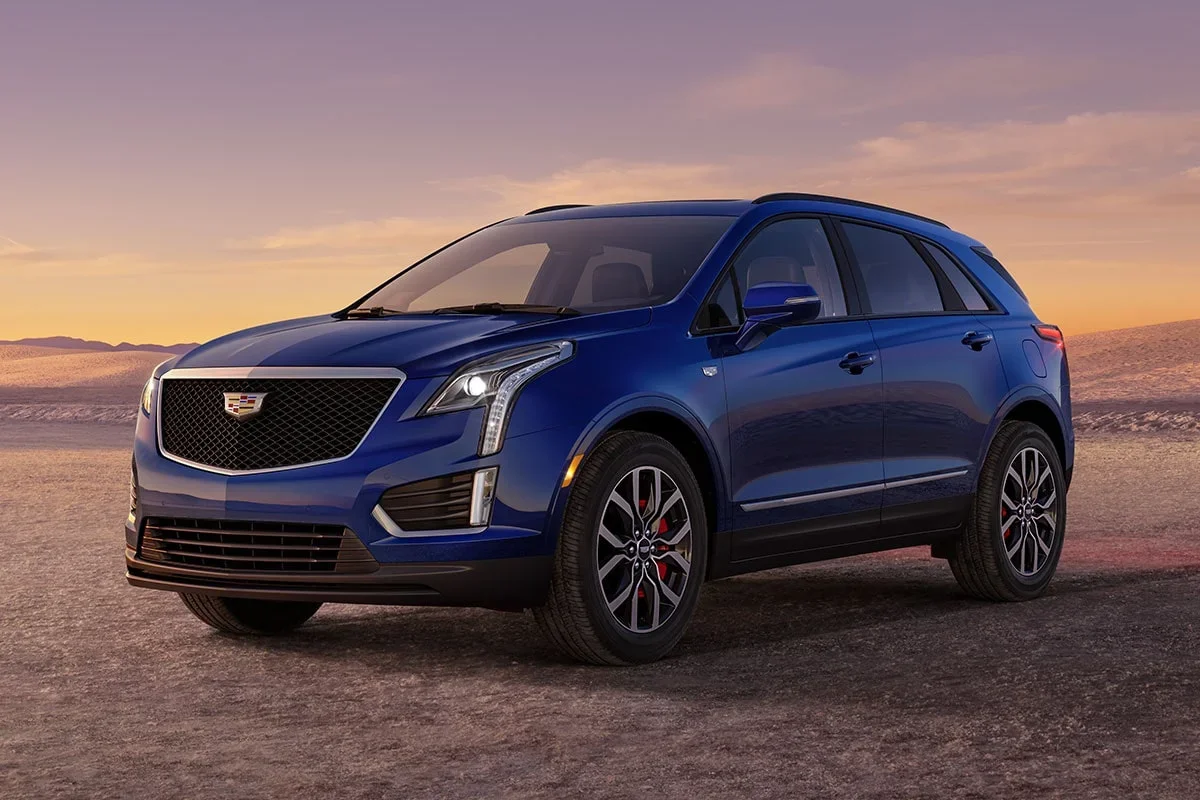
A pre-owned Cadillac can put Escalade presence, XT5 versatility, LYRIQ innovation, or V-Series performance within reach without asking you to compromise on the experience. Knowing how to finance used Cadillac models starts with more than finding a monthly payment you like. It means choosing a vehicle, loan structure, and ownership plan that all make sense together.
For shoppers across North Alabama, the best financing conversation is a clear one. You should understand what affects your approval, how a trade-in changes the equation, and why the lowest payment is not always the best fit.
Start With the Right Used Cadillac
Financing is easier to approach once you have narrowed down the type of Cadillac that fits your life. A Cadillac XT4 may make sense for a driver who wants luxury in a more maneuverable SUV. The XT5 and XT6 offer added room for families, passengers, and weekend plans. An Escalade brings commanding space and capability, while a Cadillac sedan or V-Series model may be the better answer for someone who puts driving enjoyment first.
It also helps to decide whether you are considering a standard used vehicle or a Certified Pre-Owned Cadillac. Certified vehicles are carefully inspected and include additional manufacturer-backed benefits, which can provide meaningful peace of mind. Depending on the vehicle and lender programs available, certification may also affect your financing options. The right choice depends on your desired equipment, ownership timeline, and comfort level with vehicle history.
Before applying, look beyond the vehicle's appearance and features. Review its mileage, service history, condition, available warranty coverage, and the technology you will use every day. A well-chosen used Cadillac should still feel special when you leave for work on a Monday morning or head to Decatur for the weekend.
How to Finance a Used Cadillac Step by Step
A finance application is not a commitment to buy. It is a practical way to understand the options available to you and shop with more confidence. Completing it before or during your visit allows the finance team to match your information with available lenders and explain the resulting terms clearly.
Review your credit and monthly comfort zone
Your credit profile is one of several factors lenders use when considering an auto loan. A stronger history of on-time payments and manageable existing balances can improve the options available, but shoppers with less-than-perfect credit should not assume they have no path forward. The most useful approach is to be straightforward about your situation and focus on a payment that leaves room for the rest of your life.
Start with a realistic monthly budget, then account for insurance, fuel or charging, maintenance, and registration costs. Cadillac ownership should feel rewarding, not stretched. If you are EV-curious and considering a pre-owned LYRIQ, factor in your charging routine and whether home charging equipment is part of your plan.
Bring your trade-in into the conversation
A trade-in can reduce the amount you need to finance, and it can simplify your transition from one vehicle to another. Its value is based on condition, mileage, market demand, vehicle history, and current inventory needs. Online estimates can be useful starting points, but an in-person appraisal gives you a more complete picture.
If you still have a loan on your current vehicle, the key number is your payoff amount. Comparing that balance with the vehicle's trade value shows whether you have equity to apply toward your next Cadillac or an amount that needs additional planning. A clear appraisal conversation prevents surprises later.
Choose a down payment that serves your goals
A down payment can reduce the amount financed and may help improve your loan terms. It can also lower the monthly payment without extending the loan length. That said, it is not always wise to put every available dollar toward the vehicle. Keeping an appropriate cash reserve for home, family, or unexpected expenses matters too.
There is no single right down payment for every buyer. Someone purchasing a Certified Pre-Owned XT6 for long-term family use may approach the decision differently than a driver financing a low-mileage V-Series model for a shorter ownership period. The best plan is one you can maintain comfortably.
Compare loan terms, not only payments
A longer loan term often produces a lower monthly payment, but it can mean paying more interest over the life of the loan and building equity more slowly. A shorter term may raise the payment while reducing total interest and helping you reach ownership sooner.
Ask to see how different terms affect the payment, interest cost, and estimated payoff timeline. This is especially valuable when comparing two similar used Cadillac SUVs with different mileage or certification status. A payment that looks appealing on paper may not be the best value when you consider the full term.
What Lenders Commonly Consider
Lenders review the complete application, not just one number. In general, they may consider your credit history, income, employment stability, current debts, requested loan amount, down payment, and the age and mileage of the vehicle.
Having a few details ready can make the process more efficient:
- A valid driver's license and current contact information
- Recent proof of income or employment details
- Insurance information when requested
- Trade-in registration, title information, and payoff details if applicable
If your financial situation includes variable income, a recent move, or a credit challenge, say so early. A knowledgeable finance professional can explain what documentation may help and which financing structure is worth considering. Honest context is more useful than trying to fit your circumstances into a one-size-fits-all answer.
Avoid These Used Car Financing Mistakes
The first mistake is shopping by payment alone. Monthly payment matters, but it should be evaluated alongside loan length, interest rate, down payment, and the vehicle's total fit for your needs. A slightly higher payment for a shorter, more favorable term may be the more comfortable long-term decision.
The second is skipping the test drive because the payment appears workable. A used Cadillac should earn its place in your driveway. Test its seating comfort, visibility, cargo access, infotainment functions, ride quality, and the driver-assistance features that matter to you. If you are cross-shopping an XT5, XT6, or Escalade, drive them back to back if possible. The differences are easier to feel than to read about.
The third is overlooking ownership protection. Ask about available warranty coverage, service history, and maintenance needs before you finalize the loan. Certified Pre-Owned Cadillac models can be particularly appealing to buyers who value added inspection standards and coverage, but the right answer depends on the individual vehicle and your plans for it.
Finally, do not wait until the last minute to ask questions. You deserve to know how your rate was determined, whether there is a prepayment penalty, how your trade-in is being applied, and what paperwork you will need. The best financing experience is built on clarity, not pressure.
A More Personal Way to Finance Your Cadillac
At Bentley Cadillac, financing is part of the same relationship-driven experience as choosing the vehicle itself. Whether you are coming from Madison, Athens, Hartselle, or elsewhere in the Huntsville area, the goal is to help you consider your options at your pace and make a decision you can feel good about after the keys are in your hand.
A used Cadillac is not simply a practical purchase. It can be the SUV that carries your family comfortably, the EV that changes your daily commute, or the performance vehicle that gives every open stretch of road a little more character. Browse the available used and Certified Pre-Owned Cadillac selection, schedule time behind the wheel, and apply for financing when you are ready to have a straightforward conversation about what fits.
Frequently Asked Questions
Can I apply for used Cadillac financing online before visiting Huntsville?
Yes. Bentley Cadillac offers an online finance application, so you can start from Madison, Athens, Decatur, or anywhere in North Alabama before you visit. Applying is not a commitment to buy. It helps the finance team review options with available lenders and explain the terms when you come in for a test drive.
Should I get preapproved by my bank or credit union first?
A preapproval from your bank or credit union gives you a useful point of comparison. You can still let the dealership finance team check its lender options and compare the rate, term, and total cost side by side. Choose whichever offer gives you the best overall value, not just the lowest monthly payment.
What do I need to finance a used Cadillac if I recently relocated to Huntsville?
Bring a valid driver's license, proof of income or employment, proof of insurance, and your current address. If you recently moved for work at Redstone Arsenal or elsewhere, an offer letter or recent pay stubs can help. Mention the move early so the finance team can explain what documents lenders may need.
Is a certified pre-owned Cadillac easier to finance than a regular used one?
Not always, but certification can help. Some lenders and manufacturer programs offer special terms on certified pre-owned vehicles, and those offers change over time. Ask the Bentley Cadillac finance team whether any certified offers apply to the vehicle you want and compare them with standard used financing.